Finance News
The Weekly Finance Briefing: How to Build the Habit
A fixed weekly reading slot beats constant scrolling. Here is how to set one up and keep it.
November 10, 2026
A fixed weekly reading slot beats constant scrolling. Here is how to set one up and keep it.
A structured investment decision review process turns a losing trade into a transferable lesson — if the review separates decision quality from outcome.
Consensus targets, revenue estimates and valuation math for NVDA, separated from the assumptions that carry them.
How AI models approach fixed income forecasting, why traditional models struggle, and how to judge any claimed edge.
Machine-learning models ingest more data than any econometric equation, but forex remains one of the hardest forecasting problems in finance.
Every stock exchange sets its own hours on its local clock. Here is what a trading day is, why sessions differ by city, and how holidays change the schedule.
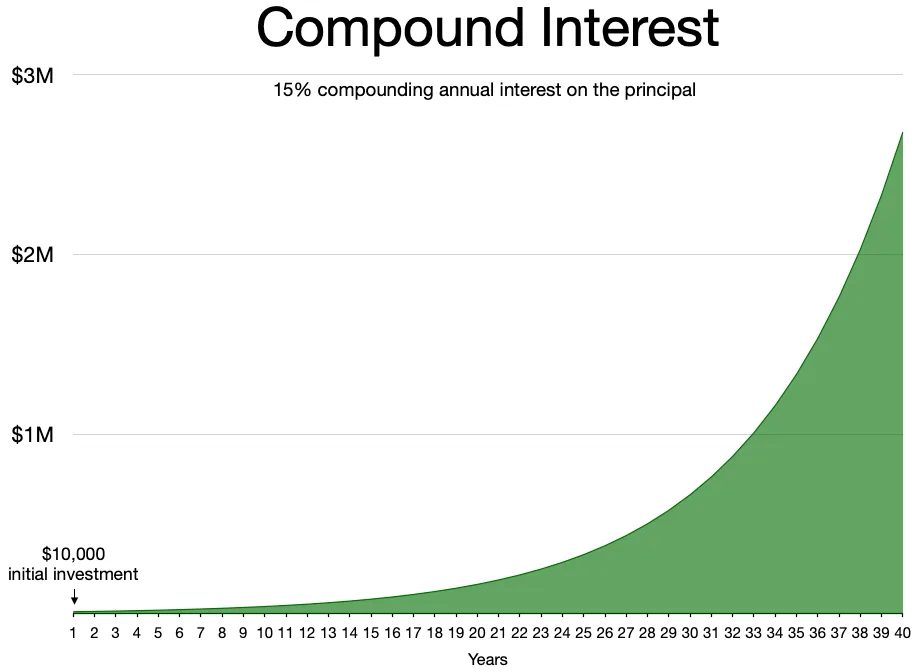
Compound interest pays you on your past gains. See a simple example, the Rule of 72, and why time matters more than clever picks.
Reported Sharpe ratios inflate with every unreported trial, and the corrections that account for this are arithmetic, not opinion.
The headline number is a household survey statistic with a narrow definition of unemployment. Knowing what sits inside it — and what sits outside — changes how…
A plain-language look at how rising prices are measured, what pushed them up after 2021, and why a little inflation is considered healthy.
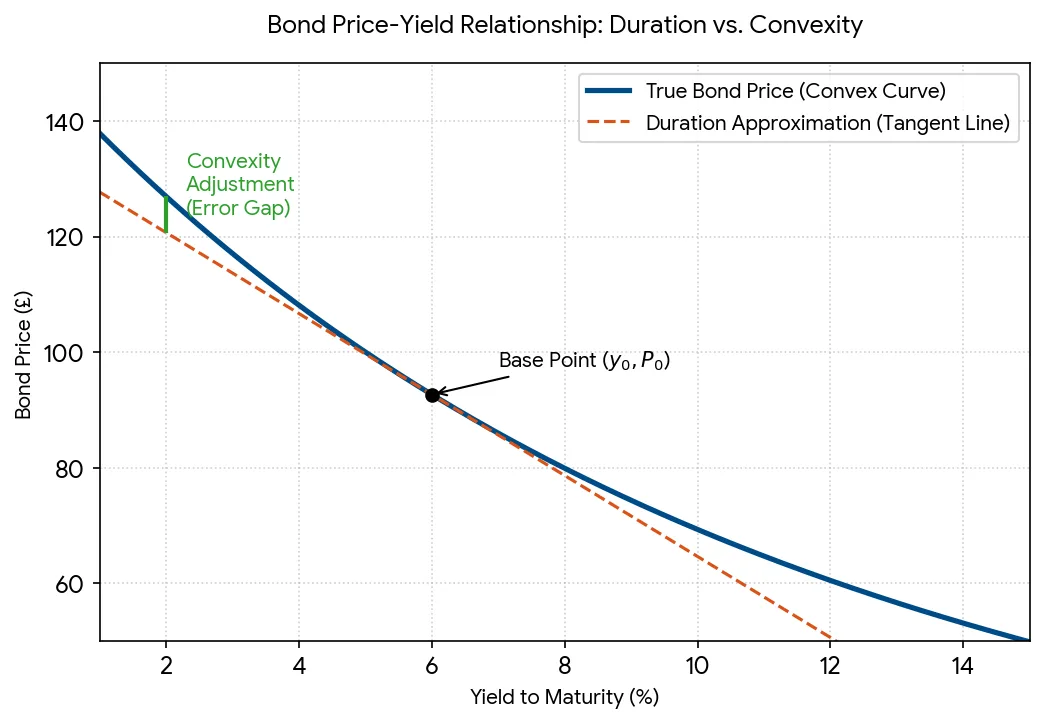
A fund's duration number looks abstract until rates move. What it measures, Macaulay versus modified, and where the number stops working.
Out-of-sample scoring is the only published test that approximates live trading, and most papers still manage to overstate it.
Two advisers paid penalties in March 2024 for overstating their use of machine learning, and the orders turn on the gap between claimed and actual model use.
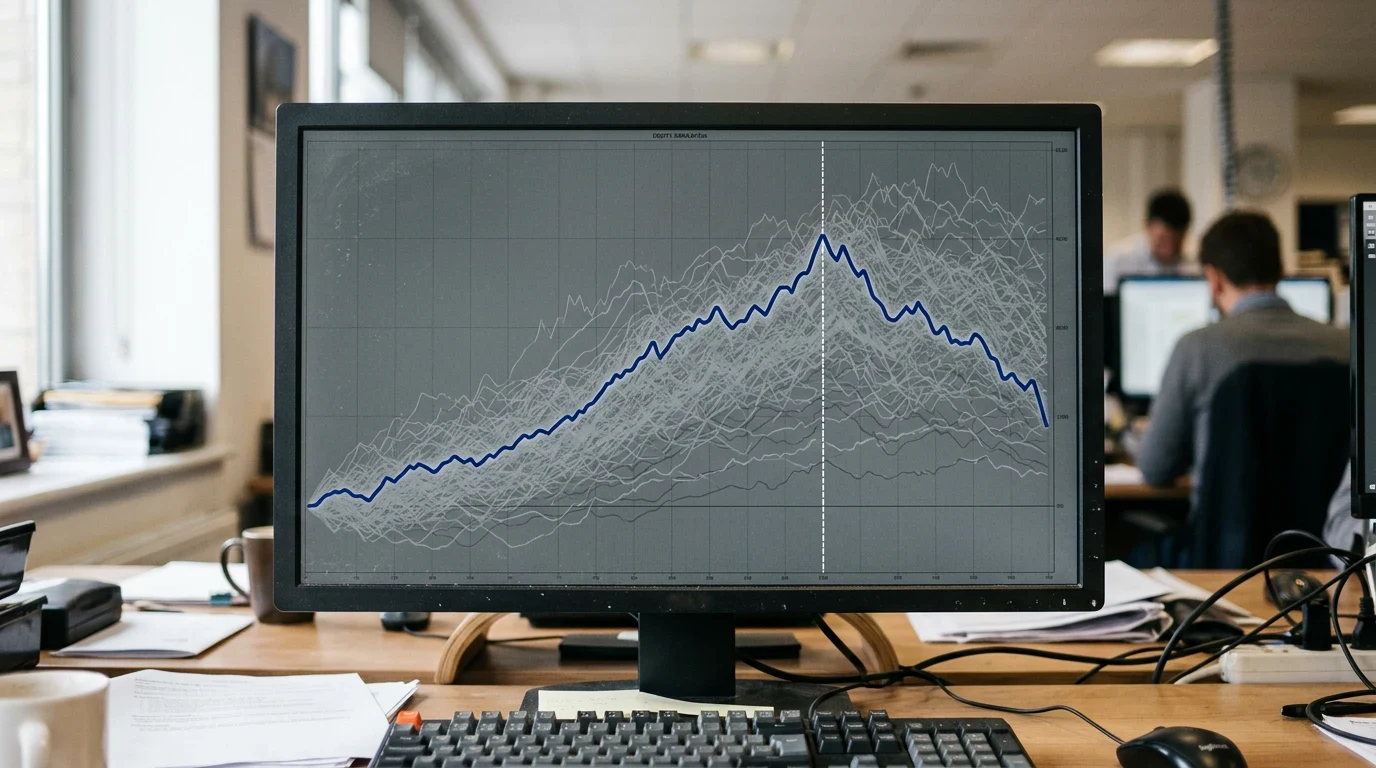
Ten trials are enough to yield an in-sample Sharpe ratio of 1.57 from strategies with zero expected out-of-sample performance. What validation, multiple-testing…
Federal regulators rewrote model risk management guidance in April 2026, keeping the same validation core built around conceptual soundness and outcomes…
Two retirees with identical average returns can end up with wildly different outcomes — the order of returns, not the average, sets the result.
A diagnostic built to answer one question a good Sharpe ratio can't: how much of a backtested strategy's performance is signal, and how much is the number of…
The March 18, 2026 statement kept the range at 3.50 to 3.75 percent, trimmed dissents to one — and added language on geopolitical developments worth reading…